As anti-migrant protests trigger arrests, closures and freight-security concerns in South Africa, regional cargo owners and transport operators face a familiar lesson: Southern Africa’s corridors are only as strong as the risk systems that keep cargo moving.
South Africa’s latest wave of unrest is forcing regional freight risk back into boardroom conversations across Southern Africa.
For cargo owners, transporters, insurers and corridor users, the issue is no longer only about road quality, border efficiency or port capacity. It is about whether regional supply chains can keep moving when the region’s largest logistics economy enters a period of social and security strain.
Police said more than 900 people were arrested during nationwide anti-migrant protests on Tuesday, June 30, after 120 marches were held across the country. Most remained peaceful, but 12 required police intervention, with arrests linked to offences including public violence, robbery, immigration violations and harbouring undocumented migrants. In Johannesburg’s Alexandra township, one person was shot dead during looting incidents targeting foreign-owned spaza shops.
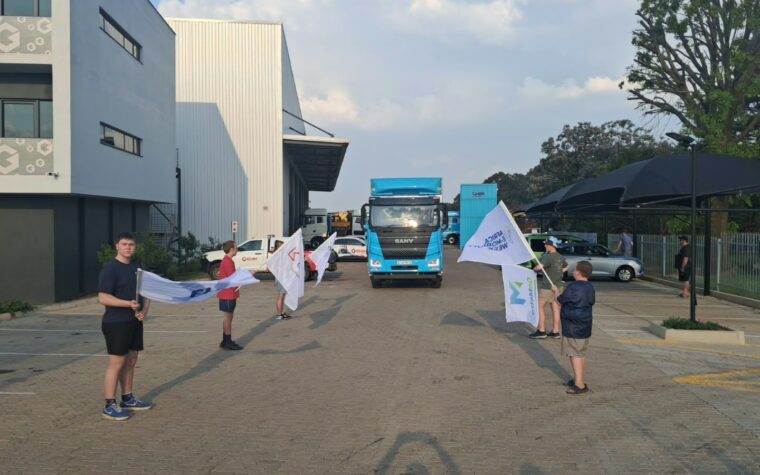
The protests followed weeks of anti-foreigner hostility, with thousands of foreign nationals fleeing ahead of the June 30 “deadline” set by the anti-migrant group March and March. Shops closed, workers stayed home and several cities prepared for disruption, while South African authorities deployed police and placed the military on standby.
For Zambia, and for the wider region that depends on South Africa’s ports, roads, warehouses, depots, financial systems, truck networks and supplier base, the commercial question is direct: what happens to regional trade when Southern Africa’s largest logistics platform becomes a higher-risk operating environment?
South Africa is not just another market in the region. It is a logistics anchor.
Its ports, warehousing base, freight-forwarding networks, trucking capacity, insurance market, OEM ecosystem, spare-parts channels and industrial suppliers support cargo far beyond its borders. For Zambian importers, miners, retailers, transporters and manufacturers, South Africa often functions as a procurement base, consolidation point, transit platform, service hub and freight gateway.
That means disruption inside South Africa rarely stays inside South Africa.
The immediate effects of unrest are practical. Freight operators may need to adjust delivery windows, avoid volatile areas, increase communication with drivers, delay dispatches, reroute cargo or consider additional security for high-value loads. The Financial Times reported that businesses, including freight operators, were preparing for possible disruption, with logistics companies adjusting deliveries and weighing additional security for drivers and cargo ahead of the protests.
This is where the story moves from politics into logistics.
Corridor risk is no longer only a border problem. It is also an urban-security problem, a driver-safety problem, a cargo-protection problem, an insurance problem and a client-communication problem.
For years, Southern Africa’s regional trade conversation has focused heavily on hard infrastructure: roads, rail, ports, one-stop border posts, inland terminals and customs systems. Those investments remain essential. But the South African unrest is a reminder that a corridor is not bankable simply because it is paved, mapped or politically endorsed.
A bankable corridor must be secure enough for cargo, predictable enough for financiers, insurable enough for underwriters and reliable enough for customers.
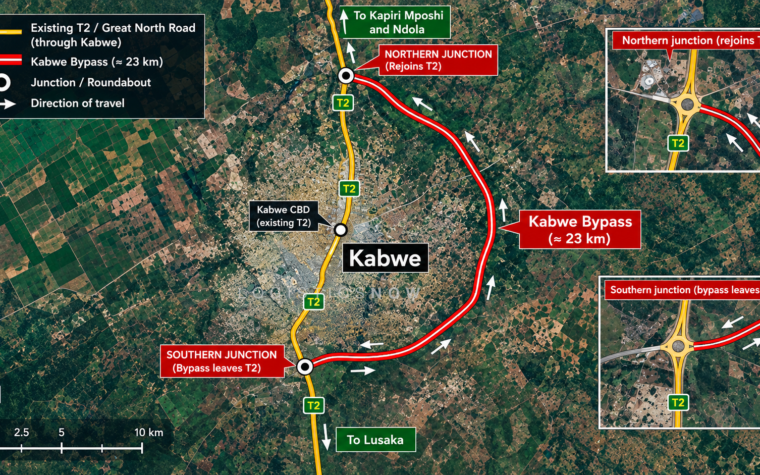
That lesson matters for Zambia because the country’s logistics strategy is increasingly tied to regional optionality. The future of Zambian trade will not be built on a single route, a single port or a single corridor. It will depend on how effectively the country can use multiple corridors, including the North-South Corridor, Lobito, TAZARA, Dar es Salaam, Beira, Walvis Bay and other routes serving the Copperbelt, DRC, SADC and wider Central African market.
South Africa remains essential to that network. But essential does not mean risk-free.
The events of the past week should push cargo owners, transporters and freight buyers to ask sharper questions. Which routes are most exposed to urban unrest? Which depots sit in higher-risk areas? Which cargo categories are more vulnerable? Which contracts allow for delay, rerouting or security-cost recovery? Which insurers require additional risk controls? Which clients expect real-time visibility when disruption occurs?
For large shippers, this is also a procurement issue. The cheapest transport quote may not be the strongest transport solution if it does not include credible route intelligence, driver support, incident escalation and continuity planning.
In a volatile corridor environment, reliability becomes a premium service.
For transporters, that creates both pressure and opportunity. The pressure is clear: security costs money, delays compress margins, drivers carry personal risk and clients still expect service continuity when conditions change. But the opportunity is just as important. Operators that can demonstrate professional risk management, real-time communication, route discipline and cargo visibility will increasingly stand apart from basic transport providers.
This is the wider strategic shift.
The next generation of competitive logistics companies in Southern Africa will not be defined only by fleet size. They will be defined by operating intelligence. The ability to know where cargo is, what risks surround it, how quickly routes can be adapted, how well drivers are protected, and how clearly clients are informed will separate basic trucking from professional corridor management.
For insurers and financiers, the same logic applies. Freight risk is no longer abstract. It has to be priced, monitored and managed. A transporter’s risk systems may soon matter as much as its asset base. A corridor’s security profile may influence not only route selection, but also insurance premiums, credit decisions, inventory planning and customer confidence.
For policymakers, the message is equally important. Regional integration cannot be measured only by infrastructure announcements and border reforms. It must also be measured by the ability of trade systems to withstand social stress, public-order disruptions and security shocks.
The current unrest in South Africa may pass. But the lesson will remain.
Regional supply chains need infrastructure, but they also need resilience. They need roads, but also risk systems. They need borders that work, but also cities and logistics nodes that remain safe enough for freight. They need competitive rates, but also transporters with the capacity to manage uncertainty.
For Zambia, the story is not that South Africa is unsafe or unusable. That would be too simplistic. The story is that regional logistics strategy must mature beyond dependence, habit and lowest-cost routing.
South Africa remains one of the region’s most important logistics platforms. But when that platform experiences social strain, the rest of the corridor feels it.
For cargo owners, transporters, insurers, financiers and policymakers, the message is clear: corridor planning must now treat security and continuity as core infrastructure.
Not after the disruption.
Before it.
A corridor is not bankable simply because it is paved. It must be secure enough for cargo, predictable enough for financiers, insurable enough for underwriters and reliable enough for customers.
Tawanda S. Hojane, Executive Publisher, Logistics Now